AI sector analysis
How transparent are banks about their business interest rates and pricing?
Of the 5 banks with a business loan, only ING mentions its own range on the page: 5.15% to 13.95%. Rabobank only provides a rate after completing the calculator (5.50% to 7.55%), ABN AMRO refers to its subsidiary New10, and Triodos Bank and Van Lanschot Kempen do not publish a rate. The 4 tested financiers (Qredits, New10, Floryn and October) all mention a percentage, although Floryn and October only mention a lower limit. None of the 10 banks with a business offering puts its rate in schema.org, the code that allows search engines and AI to read a rate directly.
Business finance sector analysis · pricing measured on 24 October 2026, ING updated on 7 November 2026
Business loan, 24 October 2026 (ING: 7 November 2026)
INGOwn range on the page5.15% – 13.95%
RabobankOnly after completing calculator5.50% – 7.55%
ABN AMRORefers to subsidiary New10New10
Triodos and Van LanschotDo not publish a rateNo rate
QreditsFinancier, fixed rate9.95%
In this article
- Calculate and compare interest
- Interest rates on business loans: which bank mentions it, and which does not
- Not a bank, but a loan: Qredits, New10, Floryn and October do show their interest rates
- Being overdrawn on your business account: what it really costs
- Business credit card with 0 per cent interest: does it exist?
- Business savings interest: from 0.75% to 1.30%, and what lies above
- Mortgage interest at 10 years fixed: what banks show
- Savings interest: what €22,900 yields
- The cheapest is not always the best: terms and disadvantages
- How many clicks does it take to find the interest rate, and can AI assistants such as ChatGPT read it?
- Website check: how fast does the page with the interest rate load?
- Interest, arrangement fees and guarantees: how to compare business loans
- How we measured this
Calculate and compare interest: business, mortgage or savings
Below you can choose between a business loan, a mortgage and a savings account. You will see what a provider charges or gives in your case, what that costs a year and what switching yields. These are ranges based on published rates per measurement date, and not a quote.
How is this calculated?
No published rate
Does not fit this amount or term
Dutch banks only leaves out providers that have been established as foreign. If that has not been established, the provider stays in. Your current bank always counts, even if it is foreign.
This is the result for these amounts:
Business · £42,000
Rates measured from 24 October 2026 to 7 November 2026
Lowest total per year first, including one-off costs
October
Business loan
- Rate
- from 2.00%
- Average interest per year over the term
- from £434
- Costs per year
- £202
- 0.04% per month on the amount borrowed
- Total per year, including one-off costs
- from £888
Per month, one-off costs and conditions
- Repayment + interest, excluding additional costs
- from £736
- One-off
- £1,260
- Your business has existed for at least 3 years, is profitable and has more than €250,000 turnover
- No personal guarantee
- One-off: 3% start-up costs
ING
Rentevastlening (Zakelijke Lening)
- Rate
- 5.15% – 13.95%
- fixed rate, excluding any rate discounts such as EIB or TLTRO
- Average interest per year over the term
- £1,146 – £3,314
- Costs per year
- not established
- Total per year, including one-off costs
- £1,188 – £3,356
Per month, one-off costs and conditions
- Repayment + interest, excluding additional costs
- £795 – £976
- One-off
- minimum £210
- Fixed-rate period 1 to 10 years
- One-off: arrangement fee at least 0.50%, with a minimum of €250
Rabobank
Business loan
- Rate
- 5.50% – 7.55%
- measured at £41,773. price indication from the online calculator, over 5 years
- Average interest per year over the term
- £1,227 – £1,711
- Costs per year
- not established
- one-off costs unknown, not included
Per month, one-off costs and conditions
- Repayment + interest, excluding additional costs
- £802 – £843
- One-off
- not established
- Your business has been trading for at least 12 months
- You can offer security, such as collateral
New10
Business loan
- Rate
- 6.00% – 12.00%
- via ABN AMRO 5.60% – 12%
- Average interest per year over the term
- £1,344 – £2,811
- Costs per year
- not established
- Total per year, including one-off costs
- £1,436 – £2,903
Per month, one-off costs and conditions
- Repayment + interest, excluding additional costs
- £812 – £934
- One-off
- £459
- For a BV: Personal guarantee of 25% of the loan amount, at least €5,000
- Annual turnover at least €50,000
- Registered for at least 12 months
- One-off: arrangement costs
Qredits
Microkrediet and MKB Krediet
- Rate
- 9.95%
- elsewhere usually between about 7.95% and 9.95%
- Average interest per year over the term
- £2,296
- Costs per year
- not established
- Total per year, including one-off costs
- £2,422
Per month, one-off costs and conditions
- Repayment + interest, excluding additional costs
- £891
- One-off
- £630
- Microkrediet: business plan needed, 10% a year early repayment without penalty after the first year
- MKB Krediet: 5% per year early repayment without penalty, the first time after one year
- One-off: handling costs
No published rate
ABN AMRO
Business loan
- Rate
- not published
- refers loans from €20,000 to €1 million to its subsidiary New10; itself on request, from €250,000
- Costs per year
- not published
Per month, one-off costs and conditions
- One-off
- not published
Triodos Bank
Business loan
- Rate
- not published
- market-rate interest and tailored terms
- Costs per year
- not published
Per month, one-off costs and conditions
- One-off
- not published
Van Lanschot Kempen
Geldlening Zakelijk
- Rate
- not published
- Costs per year
- not published
Per month, one-off costs and conditions
- One-off
- not published
Does not fit this amount or term
Floryn
Business financing
- Rate
- maximum 36 months in the online calculator
- from 4.90%
- Costs per year
- quarterly service costs, no amount given
Per month, one-off costs and conditions
- One-off
- not established
- Fixed weekly instalment of 1%, with no fixed term
- For a BV: Guarantee from 25%, at least €25,000
The order is based on the rate at the lower limit plus the known costs, with one-off costs spread over the term. If those are unknown, the row says so and they do not count. Equal monthly payments: the monthly rate is the annual rate divided by 12. Interest per year is the total interest divided by the term in years. Banks and lenders are separate sectors, with different conditions.
Mortgage · £250,000
Rates measured on 7 November 2026
Calculated over 30 years, rate fixed for 10 years Lowest interest per year first
MUNT Hypotheken
Mortgage, 10-year fixed
- Rate
- 4.46% – 4.48%
- rate at time of offer; up to 80% 4.46%, up to 90% 4.48%
- Average interest per year over the term
- £6,796 – £6,832
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- one-off costs unknown, not included
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,261 – £1,264
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £203,880 – £204,948
- One-off
- advice costs unknown
- Administration costs on acceptance €0
ING
Repayment mortgage, 10-year fixed
- Rate
- 4.48% – 4.49%
- including 0.25% Active Current Account Discount, energy label A; published for up to 85% and up to 90%, below that not established
- Average interest per year over the term
- £6,832 – £6,849
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- Total per year, including one-off costs
- £6,910 – £6,927
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,264 – £1,265
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £204,948 – £205,483
- One-off
- £2,339
- Self-employed: €400 surcharge
- Repayment including removal from the mortgage register €225
- One-off: advice €2,050 plus processing €750, when transferring or remortgaging; fees as of 1 August 2025
ABN AMRO
Annuïteiten Budget Hypotheek, 10-year fixed
- Rate
- 4.49% – 4.50%
- including 0.20% main bank discount, energy label A; up to 85% 4.49%, up to 90% 4.50%
- Average interest per year over the term
- £6,849 – £6,867
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- Total per year, including one-off costs
- £6,927 – £6,945
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,265 – £1,267
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £205,483 – £206,015
- One-off
- £2,339
- Self-employed: €250, €500 or €750 surcharge; €300 extra if not online
- One-off: advice €2,050 plus processing €750, if you do not yet have a mortgage with ABN AMRO
a.s.r.
ASR hypotheek, 10-year fixed
- Rate
- 4.49% – 4.52%
- via an adviser; up to 70% 4.49%, up to 90% 4.52%
- Average interest per year over the term
- £6,849 – £6,903
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- one-off costs unknown, not included
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,265 – £1,270
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £205,483 – £207,086
- One-off
- not established
ASN Bank
ASN Hypotheek, 10-year fixed
- Rate
- from 4.49%
- up to 80%; an 80-90% band is not in the rate list
- Average interest per year over the term
- from £6,849
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- one-off costs unknown, not included
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- from £1,265
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- from £205,483
- One-off
- not established
- New customers of SNS and RegioBank end up with ASN Bank; this list also applies to former SNS and RegioBank mortgages
Centraal Beheer
Leef Hypotheek, 10-year fixed
- Rate
- 4.51% – 4.53%
- discounts not included; not every row is available to new customers; up to 70% 4.51%, up to 90% 4.53%
- Average interest per year over the term
- £6,885 – £6,921
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- one-off costs unknown, not included
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,268 – £1,271
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £206,551 – £207,621
- One-off
- not established
Florius
Profijt drie + drie, 10-year fixed
- Rate
- 4.57% – 4.60%
- Florius Profijt drie + drie, energy label A; up to 85% 4.57%, up to 90% 4.60%
- Average interest per year over the term
- £6,992 – £7,046
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- one-off costs unknown, not included
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,277 – £1,282
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £209,769 – £211,381
- One-off
- not established
Rabobank
Repayment mortgage, 10-year fixed
- Rate
- 4.57% – 4.62%
- status of the discounts cannot be read from the online calculator; up to 67.5% 4.57%, up to 90% 4.62%
- Average interest per year over the term
- £6,992 – £7,082
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- Total per year, including one-off costs
- £7,069 – £7,159
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,277 – £1,285
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £209,769 – £212,458
- One-off
- £2,297
- Self-employed: €3,150 for advice and arrangement, instead of the amounts above
- One-off: advice €2,250 plus arrangement €500, when remortgaging to Rabobank; fees from 1 January 2026
Knab
Knab Hypotheek, 10-year fixed
- Rate
- 4.66% – 4.74%
- 60-70% 4.66%, 70-80% 4.67%, 80-90% 4.74%; above 80% only for existing customers
- Average interest per year over the term
- £7,154 – £7,298
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- Total per year, including one-off costs
- £7,196 – £7,395
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,291 – £1,303
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £214,614 – £218,939
- One-off
- £1,253 – £2,924
- Only via independent advisers
- One-off: advice from an intermediary, starts at around €1,500 and can rise to €3,500 or more
Obvion
Woon Hypotheek, 10-year fixed
- Rate
- 4.73% – 4.74%
- without sustainability discount and combination discount; up to 80% 4.73%, up to 90% 4.74%, below that not established
- Average interest per year over the term
- £7,280 – £7,298
- Only if the same rate applies for the whole term
- Costs per year
- no annual costs found
- one-off costs unknown, not included
Per month, one-off costs and conditions
- Repayment + interest during the fixed-rate period, excluding additional costs
- £1,301 – £1,303
- Fixed-rate period
- 10 years
- Total interest, if the rate stays the same
- £218,398 – £218,939
- One-off
- not established
No published rate
bunq
Mortgage
- Rate
- not published
- only lists types of mortgage and refers you to an adviser
- Costs per year
- no annual costs found
Per month, one-off costs and conditions
- One-off
- not established
Nationale-Nederlanden
Mortgage
- Rate
- rate not yet established
- the page does not show the rate at the moment
- Costs per year
- no annual costs found
Per month, one-off costs and conditions
- One-off
- not established
Openbank
Mortgage
- Rate
- not established
- whether Openbank offers a mortgage has not been established
- Costs per year
- no annual costs found
Per month, one-off costs and conditions
- One-off
- not established
Triodos Bank
Mortgage
- Rate
- rate not yet established
- the rate table cannot be read on the page
- Costs per year
- no annual costs found
Per month, one-off costs and conditions
- One-off
- £2,339
- Extra repayment without penalty from your own funds, always
- One-off: average prices for advice and contract; self-employed €2,600 or €3,300; Triodos gives the exact price
Van Lanschot Kempen
Mortgage, 10-year fixed
- Rate
- not established
- Costs per year
- no annual costs found
Per month, one-off costs and conditions
- One-off
- not established
Early repayment charges are not included
The order is based on the average interest per year at the lower limit, the same for all providers, because one-off costs are unknown for too many providers. The monthly payment applies to the fixed-rate period of 10 years. The average per year and the total interest only apply if the same rate holds for the whole term: we do not calculate a future rate. Banks use their own bands; each figure shows which band it is.
Savings · £19,000
Rates measured on 7 November 2026
Highest net per year first
Openbank
Open Spaarrekening
- Rate
- 2.25%
- Promotion, not included: 3.10% for the first 6 months for new customers, code WELKOM, then 2.25%
- You get per year
- + £428
- Costs per year
- £0
Per month, one-off costs and conditions
- Per month
- £36
- One-off
- £0
Santander Consumer Bank
Savings account
- Rate
- 2.20%
- Promotion, not included: up to 3.01% for the first 6 months for new customers on the first €250,000, then 2.20%
- You get per year
- + £418
- Costs per year
- £0
Per month, one-off costs and conditions
- Per month
- £35
- One-off
- £0
Bigbank
Flexible savings
- Rate
- 2.00%
- Promotion, not included: 3.00% for the first 6 months for new customers, then 2.00%
- You get per year
- + £380
- Costs per year
- £0
Per month, one-off costs and conditions
- Per month
- £32
- One-off
- £0
Centraal Beheer
RentePlús Rekening
- Rate
- 1.80%
- the source does not say whether this applies per part or to the whole balance; we calculate the whole balance
- You get per year
- + £342
- Costs per year
- not established
Per month, one-off costs and conditions
Nationale-Nederlanden
Internetsparen
- Rate
- 1.30% – 1.70%
- each part of the balance has its own rate: up to €10,000 1.70%, up to €25,000 1.55%, up to €100,000 1.45%, above that 1.30%
- You get per year
- + £307
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £26
- One-off
- not established
bunq
Savings account
- Rate
- 1.51% – 1.61%
- 1.61% on the first €10,000 and 1.51% on the rest, up to €100,000. This applies if your balance stays below your threshold. Above €100,000 no interest on that part. Promotion, not included: 3.11% on all your savings until the next 1 January or 1 July, then 3.11% only above your threshold
- You get per year
- + £295
- Costs per year
- £0
- bunq Free costs €0
Per month, one-off costs and conditions
- Per month
- £25
- One-off
- not established
- Maximum 3 withdrawals per calendar month
- All rates variable and gross
Garanti BBVA International
Gouden Internet Rekening
- Rate
- 1.55%
- Promotion, not included: 3.00% for the first 6 months for new customers; the bank may end the offer early
- You get per year
- + £295
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £25
- One-off
- not established
NIBC
Savings account
- Rate
- 1.55%
- no bands
- You get per year
- + £295
- Costs per year
- £0
Per month, one-off costs and conditions
- Per month
- £25
- One-off
- not established
Rabobank
Rabo SpaarRekening
- Rate
- 1.40%
- You get per year
- + £266
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £22
- One-off
- not established
Revolut
Dagelijkse Spaarrekening
- Rate
- 1.25% – 2.50%
- Standard plan: 2.50% up to €2,500, 1.25% above that. Paid plans have other rates: Plus €48, Premium €132, Metal €240, Ultra €780 per year
- You get per year
- + £264
- Costs per year
- £0
- Standard plan is free of charge
Per month, one-off costs and conditions
- Per month
- £22
- One-off
- not established
ASN Bank
ASN Sparen
- Rate
- 1.30%
- You get per year
- + £247
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £21
- One-off
- not established
Brand New Day
Savings account
- Rate
- 1.30%
- no bands
- You get per year
- + £247
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £21
- One-off
- not established
RegioBank
Spaar-op-Maat Vrij
- Rate
- 1.30%
- You get per year
- + £247
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £21
- One-off
- not established
SNS
SNS Internet Sparen
- Rate
- 1.30%
- You get per year
- + £247
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £21
- One-off
- not established
ABN AMRO
Direct Sparen
- Rate
- 1.25%
- You get per year
- + £238
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £20
- One-off
- not established
Knab
Flexibel Sparen
- Rate
- 1.25%
- You get per year
- + £238
- Costs per year
- £60
- Personal account €6 per month, free for 12 months for now; the page does not say whether it is required
- With package, per year
- + £177
Per month, one-off costs and conditions
- Per month
- £20
- One-off
- not established
Triodos Bank
Internet Sparen
- Rate
- 1.10%
- You get per year
- + £209
- Costs per year
- £0
- deposit and withdraw money free of charge; opening and keeping the account free
Per month, one-off costs and conditions
- Per month
- £17
- One-off
- £0
- According to the bank, the rate can also be negative above a certain balance
- Dutch deposit guarantee up to €100,000
ING
Oranje Spaarrekening
- Rate
- 1.00%
- You get per year
- + £190
- Costs per year
- not established
Per month, one-off costs and conditions
- Per month
- £16
- One-off
- not established
- Always linked to a current account
- Up to €10,000, ING Extra adds 0.50% or ING Max adds 1.00%
N26
Instant Savings
- Rate
- 0.25% – 0.30%
- free Standard plan: the source gives 0.25% in the table and 0.30% in the footnote. Other plans: Smart €59 per year 0.25% or 0.30%, Go €119 per year 0.50% or 0.55%, Metal €203 per year 1.50%
- You get per year
- + £48 – + £57
- Costs per year
- £0
- Standard plan is free
Per month, one-off costs and conditions
- Per month
- £4 – £5
- One-off
- not established
No published rate
Raisin
Savings platform
- Rate
- not established
- platform, not its own savings account: highest instant-access rate 2.45%. Promotion, not included: 3.30% for the first three months for new customers
- Costs per year
- not established
Per month, one-off costs and conditions
- One-off
- not established
Trade Republic
Interest on balance
- Rate
- not established
- regular rate not established. Promotion, not included: 3% on your balance up to €50,000 for new customers
- Costs per year
- £0
- no monthly subscription costs
Per month, one-off costs and conditions
- One-off
- not established
The order is based on the rate at the upper limit minus the known costs. Interest per year is balance times rate, without compound interest. We assume the rate for your balance band applies to your whole balance: the banks do not always say so. Balance exactly on a boundary: the rate of the lower band, unless the bank states otherwise. For bunq we calculate per part, as bunq does. Promotional rates do not count. For N26 and Revolut the order is based on the free plan; whether the Knab package is needed has not been established, so the order is without the package.
Amounts converted from euros at the ECB rate of 10 November 2026
Your bank
- Rate
- Costs per year
Per month, one-off costs and conditions
- Fixed-rate period
- Total interest, if the rate stays the same
- One-off
This is a calculation example, not a quote. What you pay or receive depends on your situation and the provider. EQwise has researched and calculated the rates as carefully as possible, but rates change and there may be errors. Therefore, we cannot guarantee accuracy and are not liable for errors, or for decisions you make based on this calculator. Always check the rates with the provider.
Banks
Interest rates on business loans: which bank mentions it, and which does not
This is a sector analysis. We have compared the sites of 13 banks and 4 other business financiers in the Netherlands for three products: the business loan, being overdrawn on your business account and the business savings account. The goal: to show what you as an entrepreneur find out in advance about the interest and costs, where the terms are located, how fast the page loads and whether an AI assistantAI Assistant An AI assistant is a chat program such as ChatGPT, Claude, Gemini, or Perplexity that you can ask a question in natural language and receive a written answer. can read the interest rate. With that knowledge, you can compare providers yourself and see how your own site would perform in your industry. An asterisk (*) next to a figure means: converted by us from per month to a year (monthly figure × 12).
We looked at 13 banks. Five of them offer a business loan: ING, Rabobank, ABN AMRO, Triodos Bank and Van Lanschot Kempen. The other eight do not have a business term loan: ASN Bank, SNS, RegioBank, bunq, Knab, Revolut, N26 and Openbank. You can read which banks ChatGPT and other AI assistants mention themselves in Which bank does the AI mention? Below is what the five show for a loan of €50,000 over 60 months.
ING and Rabobank
ING mentions a fixed interest rate between 5.15% and 13.95% a year, with a fixed-rate period of 1 to 10 years. These rates exclude any interest discounts such as EIB or TLTRO. On 24 October 2026, the lower limit here was still 4.6%. ING publishes 5.15% for quotes from 2 November 2026. ING writes: “When taking out or increasing credit, you pay a one-off arrangement fee”, of “at least 0.50% of the limit (increase) with a minimum of €250”. In addition, ING writes: “Often without annual accounts.”
Rabobank only shows the interest rate after you complete a calculator. For the loan purpose “Other reason”, €50,000 and a term of 5 years, a price indication of 5.50% to 7.55% was produced. Your business must have been active for at least 12 months and you must be able to provide security, such as collateral.
ABN AMRO
For loans between €20,000 and €1 million, ABN AMRO refers to its subsidiary New10. ABN AMRO itself shows “On enquiry”, from €250,000. The New10 loan is on the ABN AMRO page with an interest rate between 5.6% and 12%. The arrangement fees are “€250 (loan up to €50,000)” or “€550 (loan from €50,000 to €100,000)”. For a private limited company (bv), a personal guarantee of 25% of the loan amount is required, with a minimum of €5,000.
New10 is counted once in this article, further on with the other financiers. The figures via ABN AMRO and those on New10’s own site concern the same provider and differ from each other. This is explained there.
Triodos Bank and Van Lanschot Kempen
Triodos Bank does not mention a percentage. There is a “market-conforming interest rate” and customisation, from €50,000, with additionally, among other things, an arrangement fee, commitment fee and a fee for early repayment. Van Lanschot Kempen writes: “that is why we do not publish fixed rates for the Business Loan”.
Where a percentage is stated, it is a range. Which part of it you get depends on your company. ABN AMRO writes: “The interest rate depends on the creditworthiness of your company and the amount of the loan.”
Financiers
Not a bank, but a loan: Qredits, New10, Floryn and October do show their interest rates
All four of these financiers mention a percentage for a business loan on their own site. Floryn and October only mention a lower limit. Floryn does not mention it on the product page, but on /bedrijfsfinanciering: 0.39% per month (4.68% a year*) is visible, 4.9% a year is in a collapsed box.
What these financiers are
They are parties that lend money to entrepreneurs but are not banks. This is how they describe themselves on their own sites.
- Qredits writes: “Qredits is a non-profit foundation.” It borrows money itself from banks and institutions: “We also have to pay interest on those loans ourselves.”
- Floryn says: “We are not a bank, but entrepreneurs.” Investors can invest in a diversified portfolio of over 4,000 SME companies via Floryn, from €100,000.
- New10 is, according to itself, “a subsidiary of ABN AMRO Bank”.
- October allows private lenders to participate in projects open to them. October’s management automatically co-lends in the projects, and institutional investors lend via a fund to all projects on the platform. October has an English and a French site, no Dutch one.
This is a separate sector. Terms, costs and durations are different, so the figures below cannot be compared one-to-one with the bank figures. We say nothing here about supervision and licences: we have not assessed that.
What they mention at €50,000 over 60 months
- Qredits: 9.95% on an annual basis, both for the SME Credit (€50,000 to €250,000) and for the Microcredit (maximum €50,000). According to the frequently asked questionsFAQ A list of frequently asked questions and concise answers, usually on a separate page or at the bottom of a page., an SME Credit is “a loan of more than €50,000”, so €50,000 lies exactly on the boundary between the two. Elsewhere it says “usually between approximately 7.95% and 9.95% a year”.
- Floryn: only a lower limit, “from 4.9% a year” and “from only 0.39% interest per month” (4.68% a year*). Floryn does not mention an upper limit.
- New10: on its own site a fixed interest rate between 6% and 12% on the product page, with “fixed interest rate of 5 to 12%” also on the same page. The front page mentions 4.7% to 12%.
- October: “Rates start at 2% p.a.” Also no upper limit.
So on New10’s own site it says 6% to 12% for the loan and 4.9% to 7% for the credit. Via ABN AMRO it says 5.6% to 12% and 4.6% to 6.7%. It is the same provider, with mutually different figures. At Qredits, New10, Floryn and October, the measurement found the percentage within 1 or 2 clicks from the front page: Qredits and New10 1, October 2, Floryn 1 for the 0.39% per month and 2 for the 4.9% a year in a collapsed box.
All providers side by side, from lowest to highest lower limit. Banks and other financiers are separate sectors: compare the figures with that caveat.
| Provider | Lowest | Highest | Type and caveat |
|---|---|---|---|
| October | 2% | no upper limit | financier; plus 3% set-up costs and 0.04% per month (0.48% a year*) |
| Floryn | 4.9% a year | no upper limit | financier; maximum 36 months |
| ING | 5,15% | 13,95% | bank; range on the page |
| Rabobank | 5,50% | 7,55% | bank; only via calculator |
| New10 | 6% | 12% | financier, subsidiary of ABN AMRO; via ABN AMRO 5.6% – 12% |
| Qredits | 9,95% | 9,95% | financier; fixed rate |
| Triodos Bank | — | — | bank; does not publish a rate |
| Van Lanschot Kempen | — | — | bank; does not publish a rate |
Credit
Being overdrawn on your business account: what it really costs
Being overdrawn is called a business overdraft facility. Among the banks, ING mentions a variable debit interest rate of 4.45% to 13.95%, Rabobank gives a rate via the calculator (5.02% to 6.97%) and ABN AMRO refers to New10 (4.6% to 6.7%). Triodos Bank and Van Lanschot Kempen do not mention a percentage.
| Provider | Interest as mentioned | A year | Caveat |
|---|---|---|---|
| ING | 4.45% – 13.95% | 4.45% – 13.95% | variable; plus 0.50% to 2.00% commitment fee on the undrawn part; rates from 2 November 2026 |
| New10 via ABN AMRO | 4.6% – 6.7% | 4.6% – 6.7% | plus maximum 0.2% service costs per month on the limit (2.4% a year*, at €50,000 maximum €1,200 a year*); own site 4.9% – 7% |
| Rabobank | 5.02% – 6.97% | 5.02% – 6.97% | only via calculator; plus €27 – 40 credit commission per month (€324 – 480 a year*) |
| Floryn | 1.08% – 1.43% per month | 13.0% – 17.2%* | financier; monthly cost percentage, measured at 12 months |
| Qredits Flexible Credit | 1.1% per month | 13.2%* | financier; plus 2% management costs a year; maximum €25,000 |
| Triodos Bank | — | — | does not publish a rate |
| Van Lanschot Kempen | — | — | Euribor plus a margin that is not published |
Banks
ING mentions a variable debit interest rate of 4.45% to 13.95% a year, for quotes from 2 November 2026. This is composed of the 1-month Euribor (November 2026: 2.429%), the ING RC Market Surcharge (November 2026: 0.25%) and an individual customer margin. A commitment fee of 0.50% to 2.00% is added to this, on the part of the limit that you do not draw. On 24 October 2026, it also stated that your turnover per month must be at least 25% of your credit limit. Rabobank gave via the calculator (loan purpose “Working capital”, €50,000) an interest rate of 5.02% to 6.97%, plus a credit commission of €27 to €40 per month (€324 to €480 a year*).
ABN AMRO refers to New10 for the credit: an interest rate between 4.6% and 6.7%, “Service costs of maximum 0.2% on the agreed credit limit” and a minimum turnover of €50,000. A personal guarantee is only required for a private limited company (bv). Van Lanschot Kempen links the interest rate to the 3-month Euribor rate with a margin, but does not publish that margin. ASN Bank has a Business Credit, but you can no longer take it out.
Financiers (separate sector)
The other financiers mention more. It remains a separate sector, so do not compare their figures one-to-one with those of the banks.
- Qredits Flexible Credit: 1.1% per month on the drawn amount (13.2% a year*), “Management costs: 2% a year” and one-off handling costs of €375 to €650. The maximum is €25,000 and the term maximum 2 years, so €50,000 does not fit.
- New10: on its own site a variable interest rate between 4.9% and 7%, with “maximum 0.2% service costs per month on your total credit limit”, even if you do not draw anything: maximum 2.4% of the limit a year*. The calculator (working capital, €50,000) gave 5.29% to 5.89% and €78 service costs per month (€936 a year*).
- Floryn: no percentage on the credit page. The calculator gave, in the default setting of 12 months, a monthly cost percentage of 1.08% to 1.43%, 13.0% to 17.2% a year*.
- October does not offer an overdraft facility.
Pay attention to the units. Qredits Flexible charges 1.1% per month, Floryn mentions a monthly cost percentage (1.08% to 1.43% for the credit, 13.0% to 17.2% a year*; 1.21% to 1.56% for the loan in the calculator, 14.5% to 18.7% a year*), and at New10 service costs per month are added to the interest. So do not put 1.1% per month next to 4.45% a year: 1.1% per month is 13.2% a year*. The column “A year” in the table above converts all monthly figures in this way.
Credit card
Business credit card with 0 per cent interest: does it exist?
You will not find a business credit card with 0 per cent interest as an offer at Dutch banks. None of the 13 banks mentions a 0% interest rate on its site, and American Express does not either. What does exist: you pay no interest as long as you repay the entire amount on time. With the Rabo BusinessCard, the amount is automatically debited from your business account at the end of the month. With the ICS cards, you pay within the payment term, standard 21 days after the account statement, by direct debit or bank transfer.
What a business credit card costs, and what is stated about interest
| Provider | Card | Costs | What is stated about interest or late payment |
|---|---|---|---|
| ING | Businesscard | €39.95 a year | late payment costs: 1.20% of the outstanding balance |
| Rabobank | Rabo BusinessCard | €3 per month (€36 a year*) | automatically debited at the end of the month; no interest mentioned |
| ABN AMRO | Business Card, issued by ICS | €37.50 a year | first year 50% discount for business customers; no interest mentioned |
| Knab | Creditcard Zakelijk, via ICS | €37.50 a year, €40 from 1 November 2026 | 21 days to repay free of charge; late: €5 plus 14% debit interest; staggered payment is not possible |
| SNS | ICS Visa World Card Business | €42 a year | no interest if you top up the balance on time; no percentage mentioned |
| ASN Bank | ICS Visa World Card Business | not on the page | no interest if you top up the balance on time; no percentage mentioned |
| bunq | business card | Free Business free; paid plans €7.99 to €23.99 per month | prepaid, no credit limit |
| American Express (not a bank) | Business Gold Card | €270 a year | deferred payment of 30 to 50 days; no interest mentioned |
Triodos Bank (“does not offer a credit card”), Van Lanschot Kempen (only a credit card with the private current account), Revolut and N26 (only debit cards) do not have a business credit card. At Openbank we found no business offering, and RegioBank is now ASN Bank.
The small print at ICS
For the ICS card from SNS and ASN Bank, the rules are in the ICS terms and conditions for the Visa World Card Business (July 2026 version). There, interest runs from the day of each purchase, at the statutory interest rate plus the highest surcharge allowed by the Credit Compensation Decree. The terms and conditions do not mention a fixed percentage. ICS waives that interest if you pay the entire balance within the payment term. If you only pay a part, the waiver lapses completely and you pay all interest, plus administration costs. “0 per cent” therefore only applies to this card as long as you repay everything in full on time every time.
Therefore, before you apply for a card, check the terms and conditions to see how long you have to pay the entire balance, and what it costs if you fail to do so once. This section was measured on 30 October 2026; at * we have converted from per month to a year ourselves.
Savings
Business savings interest: from 0.75% to 1.30%, and what lies above
Ten banks mention a business savings rate. For seven of them, the interest on €25,000, instantly accessible, is between 1.10% and 1.30%, and bunq mentions 0.75%. Higher rates only apply with a condition: Van Lanschot Kempen with invested assets, Revolut depending on “the type of plan you have” (Grow €35 per month, €420 a year*). The highest interest rate without a promotion or subscription is 1.30%, at Rabobank, ASN Bank and SNS. We read the rates of Triodos Bank, SNS and bunq on 7 November 2026.
| Bank | Interest on €25,000 | Condition |
|---|---|---|
| Revolut | 1.4% – 2.5% | depends on “the type of plan you have”; Grow €35 per month (€420 a year*) |
| Van Lanschot Kempen | 1,70% | only with Wealth Management Arrangement, otherwise 1.20% |
| Rabobank | 1,30% | none |
| ASN Bank | 1,30% | only with business current account from ASN; from €25,000 1.20% |
| SNS | 1,30% | only with an SNS ZZP Account or Business Account; from €25,000 1.20% |
| ABN AMRO | 1,25% | for business customers of ABN AMRO |
| Knab | 1,25% | subscription €7 (sole trader) or €11 (bv) per month, €84 or €132 a year* |
| ING | 1,10% | none |
| Triodos Bank | 1,10% | interest as of 1 November 2026; on 24 October 2026 this was 0.90% |
| bunq | 0,75% | variable, for Business accounts |
Revolut has a promotion of 5.25% for new customers, from 15 September to 15 November 2026. N26 shows no business savings percentage.
Mortgage
What do banks show for a mortgage with 10 years fixed interest?
With 10 years fixed interest, each provider mentions the rate for its own tier and with its own discount. The numbers are therefore not directly comparable. On 7 November 2026, we read the annuity rates without NHG from 10 providers. Up to 90% of the property value, they range from 4.48% at MUNT to 4.74% at Obvion and at Knab, which only mentions 4.74% for existing customers. At ING and ABN AMRO, a discount is included in the figure.
In the calculator at the top of this article you can see what a mortgage costs a year in your case and what switching yields.
| Provider | Tier | Rate 10 years fixed | Discount or condition in the figure | Date on source |
|---|---|---|---|---|
| MUNT | up to 90% | 4,48% | quote interest: daily rate plus 0.15% | 7 November 2026 |
| ING | up to 90% | 4,49% | yes, Active Current Account Discount of 0.25%, energy label A. Not read without discount. | 7 November 2026 |
| ABN AMRO | up to 90% | 4,50% | yes, house bank discount of 0.20%, Annuities Budget Mortgage, energy label A | 7 November 2026 |
| ASN Bank | up to 95% (the list has no separate tier 80-90%) | 4,51% | not established | 6 November 2026 |
| a.s.r. | up to 90% | 4,52% | no discount mentioned, take out via an adviser | 6 November 2026 |
| Centraal Beheer | up to 90% | 4,53% | discounts not yet processed. Not every row can be taken out for new customers. | undated |
| Florius | up to 90% | 4,60% | Profijt drie + drie, energy label A | undated |
| Rabobank | up to 90% | 4,62% | cannot be read. Current account package (0.20%) and sustainability (0.15%) are choices on the page. | 7 November 2026 |
| Knab | 70 to 80% | 4,67% | not established | 6 November 2026 |
| Knab | 80 to 90% | 4.74%, only for existing customers | not established | 6 November 2026 |
| Obvion | up to 90% | 4,74% | without sustainability discount | 5 November 2026 |
Knab only offers the mortgage via independent advisers. After 22 September 2026, according to ASN Bank, no separate interest lists have been drawn up for SNS, RegioBank and BLG Wonen. ASN Bank’s rates also apply to their former mortgages. Aegon refers to a.s.r. Van Lanschot Kempen’s rate is 4.88% with maximum 65% financing, energy label B and with an arrangement of 0.2% for entrepreneurs, professionals and medical professionals. It is therefore not comparable with the rates in the table. At Triodos Bank we could not read the percentages. At Nationale-Nederlanden, the page showed no current interest rates. At bunq we found no rate. At Openbank we found no mortgage, but that has not been established.
What does a mortgage cost besides the interest?
At ING, Rabobank and ABN AMRO, one-off advice and arrangement fees of €2,100 for a first mortgage are on the page. Triodos Bank mentions an average of €2,100 for those who have not bought a home before and €2,800 for those who have. We found no ongoing annual costs for the mortgage itself at any of the providers whose costs we read: ING, Rabobank, ABN AMRO, Knab, Triodos Bank and MUNT. Rabobank only mentions €25 a year maintenance for an insurance policy, the mortgage protection. We have not investigated the other providers for this, or did not find them.
| Provider | Rates as of | First mortgage | Next mortgage | Entrepreneur |
|---|---|---|---|---|
| ING | 1 August 2025 | new first mortgage: €2,100 (advice €1,350 plus processing €750) | new next, porting or switching: €2,800 (€2,050 plus €750) | surcharge €400 |
| Rabobank | 1 January 2026 | starter: €2,100 (€1,800 plus €300) | purchase of new home or switching to Rabobank: €2,750 (€2,250 plus €500) | €3,150 (€2,650 plus €500) |
| ABN AMRO | no date mentioned | starter, digital: €2,100 (€1,350 plus €750) | mover, no mortgage at ABN AMRO yet: €2,800 (€2,050 plus €750) | surcharge €250, €500 or €750. Not digital: €300 extra |
The totals for ING and Rabobank are mentioned by those banks themselves. The totals for ABN AMRO are our own sum of the published amounts. Knab does not provide advice itself. According to Knab, advice costs at an intermediary start at approximately €1,500 and can go up to €3,500 or more.
What does early repayment of a mortgage cost?
At Triodos Bank, extra repayment with own funds costs nothing; at ING, an interim interest adjustment, interest averaging or deregistration from the mortgage register upon full repayment costs €225. Triodos Bank writes: “at Triodos Bank you can always make extra penalty-free repayments if you do this with your own funds. No maximum then applies and you pay no fee for early repayment.” ING’s €225 is in a table that has applied since 1 December 2022. We have not read the compensation rules of the other providers.
What does this comparison not say?
This comparison says nothing about what you pay, because the rate depends on the tier, the energy label, NHG and the discount. We do not know what rate a bank offers you. This text is not mortgage advice.
Private savings
What does €22,900 in a savings account yield?
On 7 November 2026, the regular interest for an instantly accessible savings account at €22,900 in our measurement was between 1.00% and 2.25%. The highest percentages we found, between 3.00% and 3.30%, apply temporarily.
In the calculator at the top of this article you can see what savings yield in your case and what switching yields.
The amount of €22,900 is the median of the balances per private household according to the CBS, as of 1 January 2025, provisional. The average is €58,300. The CBS describes these balances as “All balances in accounts at (savings) banks, including foreign balances.” The percentages below are variable, unless stated otherwise.
| Provider | Interest at €22,900 | What goes with it | Date on source |
|---|---|---|---|
| Openbank, Open Savings Account | 2,25% | balance up to €300,000, free, Spanish deposit guarantee up to €100,000 | undated |
| Centraal Beheer, RentePlús | 1,80% | class up to €25,000, above that 1.65%. Dutch Deposit Guarantee up to €100,000. | undated |
| Nationale-Nederlanden, Internet Savings | 1.62% average | 1.70% on the first €10,000 and 1.55% on the rest: each part of the balance has its own percentage | 26 October 2026 |
| NIBC, Savings Account | 1,55% | no tier, no costs | undated |
| Garanti BBVA International, Golden Internet Account | 1,55% | regular interest, without promotion | 28 May 2025 |
| Rabobank, Rabo Savings Account | 1,40% | class above €20,000 to €100,000. “These interest rates can change.” | after 14 October 2026 |
| ASN Bank, ASN Savings | 1,30% | class €0 to €25,000 | page: “apply from 18 November 2025” |
| SNS, Internet Savings | 1,30% | class €0 to €25,000 | 18 November 2025 |
| RegioBank, Savings-to-Measure Free | 1,30% | class €0 to €25,000 | 18 November 2025 |
| Brand New Day, Savings Account | 1,30% | no tier | 7 May 2025 |
| ABN AMRO, Direct Savings | 1,25% | €0 to €500,000 | from 29 September 2026 |
| Knab, Flexible Savings | 1,25% | package €6 per month for a private account, now 12 months free. Whether the package is necessary for savings is not stated on the page. | 22 October 2026 |
| Triodos Bank, Internet Savings | 1,10% | class €10,000 up to and including €25,000, free, Dutch Deposit Guarantee up to €100,000 | 1 November 2026 |
| ING, Orange Savings Account | 1,00% | class €10,000 to €100,000. Up to €10,000, 1.25% applies. The savings account is linked to a current account. | base interest from 18 April 2025 |
We read the rate of the class in which €22,900 falls as valid for the entire balance, unless the bank itself says that each part has its own percentage. The pages of ING, Rabobank, ASN Bank and Centraal Beheer do not say whether that is correct, and ING mentions its own percentage for the first €10,000. At Revolut and N26, the percentage depends on your subscription, which is why there is no fixed number for €22,900.
How long does a promotional interest rate last, and what follows after?
A promotional interest rate for new customers lasts 3 or 6 months with these providers, after which the regular interest rate applies. At bunq, a bonus interest rate applies until the next 1 January or 1 July.
| Provider | Promotion or bonus | Afterwards or regular | Deposit guarantee in the source | Date on source |
|---|---|---|---|---|
| Bigbank, Flexible Savings | 3.00% guaranteed, 6 months, new customers | “currently 2.00%”, interest up to €250,000, no costs | balance guaranteed up to €100,000, system and country not mentioned | undated, read 7 November 2026 |
| Santander Consumer Bank | “up to 3.01%”, 6 months, new customers, first €250,000 | base interest “currently 2.20%”, entity Open Bank, S.A., branch in Belgium | not read (collapsed FAQ) | undated, read 7 November 2026 |
| Garanti BBVA International | 3.00%, 6 months, new customers from 9 July 2026 without a savings account in the past 12 months. The bank may stop the promotion early. | Golden Internet Account 1.55%, since 28 May 2025 | not read | promotion for new customers from 9 July 2026, read 7 November 2026 |
| Raisin (platform) | 3.30% for new customers, the first 3 months | highest interest instantly accessible via the platform: 2.45% | not read | 2 November 2026 |
| Openbank, Welcome Savings Account | 3.10%, 6 months, only new customers | Open Savings Account, 2.25% | Spanish deposit guarantee up to €100,000 | undated, read 7 November 2026 |
| bunq, Savings Account | “3.11% is the gross bonus interest” on all your savings, from your first deposit until the next 1 January or 1 July. Also applies to the free subscription. | up to your threshold (highest balance of the previous half-year): 1.61% on the first €10,000 of that part and 1.51% on the rest, up to €100,000. Above the threshold: 3.11%. | not read | read 7 November 2026 |
A calculation example shows the difference. With 1.25%, €22,900 yields approximately €286 interest in 1 year. With 3.00% in the first 6 months and 2.00% in the 6 months after, as with Bigbank, that is approximately €573. This is our own calculation without compound interest and without tax, with the percentages of 7 November 2026. It is not a prediction, as the rates are variable.
Are savings at these providers guaranteed?
Whether a balance is guaranteed depends on the provider and the system, and it is not always stated on the pages we read. Openbank mentions a Spanish deposit guarantee up to €100,000. Bigbank mentions a guarantee up to €100,000 without a system or country. At Santander Consumer Bank, Garanti BBVA International, Raisin and bunq we read no guarantee.
What does this savings list leave out?
Trade Republic mentions 3% on your balance up to €50,000 for new customers. We did not read the duration and the regular interest rate, which is why Trade Republic is not in the tables. The list also does not say which provider suits your situation.
Terms and conditions
The cheapest is not always the best: terms and disadvantages
A low rate says little without the condition next to it. The terms and conditions for the savings interest are in the table above; this was stated for the loans.
For the loan
- Floryn: the calculator goes up to 36 months, and the financing has “a fixed weekly term of 1%, without a fixed duration”. For a private limited company (bv), Floryn asks for a guarantee from 25% (minimum €25,000), in special cases lower or none.
- October: the 2% is a lower limit, with “a project set-up fee (3%)” and “a monthly fee (0.04%)” (0.48% a year*). Your company must have existed for at least 3 years, be profitable and have a turnover of more than €250,000. October also gives “No personal guarantee”.
- New10: for a private limited company (bv), you are personally liable for 25% of the loan amount, with a minimum of €5,000. The annual turnover is at least €50,000 and your company has been registered for at least 12 months.
Qredits: two products
- SME Credit: 9.95%, 1.5% handling costs, the government partly guarantees via the BMKB, and you can repay 5% a year penalty-free, the first time after one year.
- Microcredit: 9.95%, “One-off handling costs of €375 to €850”, maximum €50,000, a business plan required, and annually 10% of the original principal amount penalty-free repayment, after the first year.
The percentages of ING (5.15% to 13.95%) and Rabobank (5.50% to 7.55%) are ranges that depend on your profile. So do not just compare the lowest numbers: the 2% of October and the 5.15% of ING are lower limits of products with different terms, in a different sector.
Discoverability
How many clicks does it take to find the interest rate, and can AI assistants such as ChatGPT read it?
For a human, it takes 1 to 4 clicks at the banks with a business loan to get to the rate, or to the place where it belongs. A simple visitor without JavaScriptJavaScript A programming language that makes web pages interactive, such as a drop-down menu. sees no percentage at ING, Rabobank, Revolut and October. How each AI service handles this, we have not measured: a service that reads like such a simple visitor will see the same thing.
What a human sees
We counted the clicks from the front page to the rate. A hidden menu counts, and also a box that you must first open. For the business loan: ING 2 clicks, Rabobank 2 plus the calculator, ABN AMRO 3 on desktop and 4 on mobile, Triodos Bank 1 (without rate) and Van Lanschot Kempen 4 with a collapsed box (and no rate is stated there). We also looked at whether the rate is visible as plain text, or only after a calculator, in a collapsed box or in a PDF.
What a simple visitor without JavaScript sees
We looked at whether the percentage is literally in the HTML, without executing JavaScript. We also looked at whether robots.txtRobots.txt A small file on your website that tells search engines and AI crawlers which parts they are and are not allowed to visit. allows AI bots, whether the page is in the sitemap and whether the page uses schema.orgStructured data Additional information in the code that tells search engines and AI exactly what is on a page., a fixed code with which a site makes a rate machine-readable.
- ING: a simple client received no response on any attempted ING page. To a real browser, the server sends an empty shell without interest rates.
- Rabobank: a simple client received a 403. The interest rates are also missing from the server response to a real browser.
- October: a simple client received a 403 with a browser check. In robots.txt, “Disallow: /” is set for GPTBot, ClaudeBot, PerplexityBot, Google-Extended and CCBot; ChatGPT-User, OAI-SearchBot and Claude-SearchBot are allowed.
- The other banks and financiers: at ABN AMRO, Triodos, Knab, ASN and at the financiers Qredits, Floryn and New10, the percentage is in the HTML, where they mention one. Revolut gave a simple visitor a 403. All banks with a business rate allow the eight measured AI bots in robots.txt.
Schema.org: only New10, with different values
None of the 10 banks with a business offering use schema.org for the rate. Of the other financiers, only New10 does so. On the loan page, the code shows an interest rate of 4.3 to 12, while the page shows 6% to 12% (and also “5 to 12%” on the same page). On the credit page, the code shows 4.1 to 9.6, while the same page shows “Variable interest between 4.9% – 7%” and “Competitive interest between 4.7% – 12%”.
What the AI thinks, and what is on the site
We asked AI assistants which bank for entrepreneurs is most transparent about costs: directly via the API of ChatGPT, Gemini, Claude and PerplexityPerplexity An AI search engine that provides answers with numbered citations., with and without search functionWeb search A mode of an AI assistant in which it searches the internet live while generating a response., in three formulations. This yielded 210 answers. Knab is mentioned first most often, the major banks almost never. Their names do appear, but usually for comparison.
| Bank | AI mentions it first as “most transparent” | What we found on the site |
|---|---|---|
| Knab | 63% | the business savings rate (1.25%) is simply on the site, including the subscription; no business loan |
| bunq | 20% | on 24 October 2026 no business savings rate found; the Savings Account link in the business menu goes to the private page. On 7 November 2026 we found 0.75% on the bunq help page. |
| ABN AMRO | 6% | refers to subsidiary New10 for loan and credit; itself “On enquiry” from €250,000 |
| ING | 2% | loan 5.15% to 13.95% and credit 4.45% to 13.95% on the page (read manually on 7 November 2026). On 24 October 2026, the rate was only visible after JavaScript. |
| Rabobank | 1% | loan and credit only via the calculator; no rate without filling in details |
Bunq is striking. Without search function, ChatGPT, Gemini and Claude mention bunq in 99% of the answers, with search function still in 32%. On 24 October 2026, we found no business savings rate for bunq on the site. On 7 November 2026, 0.75% was on the bunq help page. With search function, the answer shifts to Knab, the bank that puts its pricing visibly on the site. knab.nl is also the source cited most often: in 74 of the 120 answers with search function.
Own measurement via EQwise LLM data on 24 October 2026: we ask the question directly to the AI services via their API and count each answer. Repeated answers are similar, so read the percentages as a direction, not an exact value.
Why this matters
If you ask an AI assistant to compare the cheapest business loan of €50,000, and it only reads what a simple visitor sees, it cannot include an interest rate that only appears after JavaScript or is behind a 403. If the interest rate in the code is different from that on the page, the site itself provides two different figures.
Website check
Website check: how fast does the page with the interest rate load?
On mobile, for 4 out of 10 banks, the interest rate page only appears after more than 2.5 seconds, the limit Google calls good: ING (3.0 s), Triodos Bank (5.1 s), Rabobank (5.8 s) and ABN AMRO (11.5 s). ABN AMRO is only fully loaded after 30.8 seconds. On desktop, 9 out of 10 banks meet the standard; only Rabobank does not (3.5 s).
| Provider | Mobile: main content in view | Desktop: main content in view | Mobile: fully loaded |
|---|---|---|---|
| Van Lanschot Kempen | 1.2 s | 0.5 s | 7.3 s |
| bunq | 1.8 s | 0.7 s | 6.4 s |
| Knab | 1.8 s | 1.0 s | 4.9 s |
| Qredits (financier) | 1.9 s | 1.5 s | 9.7 s |
| ASN Bank | 2.0 s | 0.6 s | 3.0 s |
| N26 | 2.3 s | 0.8 s | 7.5 s |
| Revolut | 2.4 s | 1.5 s | 9.8 s |
| October (financier) | 2.8 s | 1.4 s | 7.5 s |
| ING | 3.0 s | 1.6 s | 5.3 s |
| Triodos Bank | 5.1 s | 2.5 s | 6.2 s |
| Rabobank | 5.8 s | 3.5 s | 13.5 s |
| New10 (financier) | 6.9 s | 0.8 s | 8.5 s |
| ABN AMRO | 11.5 s | 1.7 s | 30.8 s |
| Floryn (financier) | measurement aborted | measurement aborted | 10.5 s |
Measured with GTmetrix from Amsterdam on 24 October 2026: one test per page, on desktop and on a simulated iPhone 13 with 4G. At Floryn, the measurement of the main content aborted twice because the page did not settle. Financiers are a separate sector.
A slow page costs turnover: at Vodafone, a 31% faster page resulted in 8% more sales. You can calculate what it means for your site with the EQwise calculator.
You can also have such a website check done for your own site. In the free website scan, you can see how fast your site opens on a phone, in seconds and with the standard included, and what your competitor does that you do not. If you want the full picture, including technology, content, authority and AI visibilityAI Visibility How frequently and effectively your business appears in the responses provided by AI assistants., there is the SEO and GEO audit.
Compare
Interest, arrangement fees and security: how to compare business loans
You compare a loan on six things: interest, arrangement fees, security, term, monthly amount and total costs. For €50,000 over 5 years (60 months), the monthly amount is €876.39 at 2% interest a year and €1,112.22 at 12% a year. Arrangement fees, security and service costs are added to that.
Calculation example: €50,000 over 5 years
This is a calculation example, not an offer. All percentages in this article are a year, unless “per month” is stated. The term of 5 years (60 months) is only the example: one fixed case, so you can compare providers side by side. Annuity, without arrangement, handling, service or management costs. The totals are rounded to the monthly amount times 60; the average interest a year is the total interest divided by 5.
| Interest a year | Monthly amount | Average interest a year | Total over 5 years | Of which interest |
|---|---|---|---|---|
| 2% (lower limit October) | €876.39 | €516.68 | €52,583.40 | €2,583.40 |
| 12% (upper limit New10) | €1,112.22 | €3,346.64 | €66,733.20 | €16,733.20 |
These are the lowest lower limit and the highest upper limit among the four financiers, not of the market: as a bank, ING goes up to 13.95%. It remains a separate sector.
Additional costs
- Arrangement fees. ING writes: “When taking out or increasing a credit, you pay a one-off arrangement fee”, of “at least 0.50% of the limit (increase) with a minimum of €250”. ABN AMRO mentions “€250 (loan up to €50,000)” and “€550 (loan from €50,000 to €100,000)”, so exactly €50,000 falls on the boundary; New10 mentions €550 on its own site. Qredits charges 1.5% handling fees for the SME Credit. October charges 3% start-up costs, which is €1,500 for €50,000.
- Monthly costs. October charges 0.04% per month on the borrowed amount: 0.48% a year, which is €240 a year for €50,000. Floryn mentions “quarterly service costs” without an amount.
- Security. For a limited company (bv), ABN AMRO and New10 require a personal guarantee of 25% with a minimum of €5,000, and Floryn 25% with a minimum of €25,000.
- Term. Floryn goes up to 36 months in the calculator, Qredits Flexible Credit up to 2 years.
What the calculators showed
Qredits gave €1,062 per month for €50,000 over 5 years. Floryn gave costs of €11,920 to €15,070 for 36 months and one-off withdrawal, with a weekly instalment of €500. New10 gave 6.46% to 6.86% for 60 months and purpose “machines” and a first monthly amount of €1,103: €833 repayment plus €270 interest. That is a first monthly amount with linear repayment, and therefore not comparable with the annuities above. These are results from calculators, not an offer to you.
With a caveat: what you ask for yourself
The measurement shows what was on the sites on 24 October 2026, not what you would pay. Ask every provider you consider in writing for:
- the interest rate for your company, fixed or variable, and not the range;
- all one-off costs, for your loan amount;
- the monthly or quarterly costs, even if you do not withdraw anything, and whether they apply per month or a year;
- whether a guarantee is required, and for what amount;
- the term and what extra repayment costs;
- the total amount you repay over the term.
Once you have those six answers per provider side by side, you compare on what it costs you.
How do you stand compared to your competitor?
If you sell services or products yourself, you are on the other side of this comparison. The measurement shows how differently providers make their price and conditions findable, for people and for AI: one puts the rate on the page, the other behind a calculator, a collapsed section or JavaScript. A critical customer also uses an AI assistant for this, to compare and choose.
Therefore, ask yourself where you stand compared to your competitors in your own industry. You make it easier for a customer and an AI assistant with three things: pricing and conditions visible on the page, readable without JavaScript, and clear about what you do and do not do. If you want to know how your pages compare to those of your competitors, contact EQwise for a comparison within your industry.
Accountability
How we measured this
On 24 October 2026, we viewed the business rates of 13 banks and 4 other financiers (Qredits, New10, Floryn and October) on their own sites. We did not log in anywhere and did not apply for anything. We filled in calculators with the reference case of €50,000 in 60 months, without personal data and without pressing apply. We read the ING rates for the business loan and the overdraft again on 7 November 2026, manually in a normal browser, because the ING page refuses automated clients. The rest of the measurement remains that of 24 October 2026.
We viewed the business credit cards on 30 October 2026, in the same way, partly with a real browser so that text that only appears after JavaScript also counts. We read the ICS conditions in the July 2026 version.
Not every calculator has 60 months. Rabobank calculated with 5 years for the loan. For the Floryn loan, 36 months is the highest choice, and we took that. For the Floryn credit, we used the default setting of 12 months. In the New10 credit calculator, the term choice disappears; for the Rabobank credit, we only filled in the purpose working capital and €50,000. There is no calculator for the Flexible Credit from Qredits; the term there is a maximum of 2 years.
The measurement belongs to our article Which bank does the AI mention?. Rates change. Always check them on the provider’s site before making a decision.
How we get our figures
We ask the questions directly to ChatGPT, Gemini, Claude and Perplexity, via their API. Where the service allows it, we ask each question both with and without search function.
We ask the same question in multiple formulations. Each answer is counted: who is mentioned, and how often.
The date is stated with each measurement. An AI answerAI Answer The generated response provided by an AI assistant in answer to a query. is not fixed, so a measurement shows a direction and not an exact value.
What is stated about the sites themselves, such as pricing, load timeLoad time The time it takes for a page to become visible and usable., robots.txt and schema.org, we measure separately, manually or with browser tests.
Placing this graph on your own site
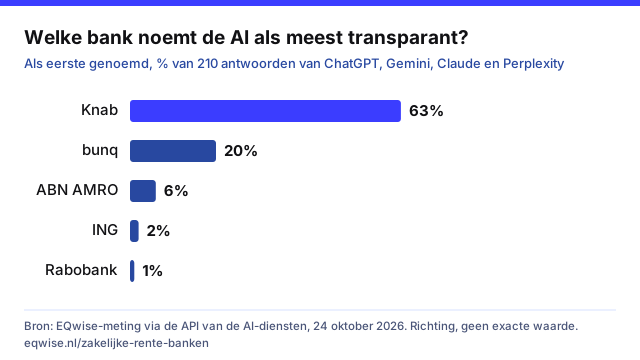
You may use this graph on your own site, in a newsletter or a presentation, with the source citation included. Copy the code below; the link to this article is already in it.
<a href="https://eqwise.nl/zakelijke-rente-banken/"><img src="https://eqwise.nl/wp-content/uploads/grafieken/ai-transparantie-banken-2026-10.svg" width="640" height="360" alt="Welke bank noemt de AI als meest transparant over zakelijke kosten? Knab 63%, bunq 20%, ABN AMRO 6%, ING 2%, Rabobank 1%. Bron: EQwise, 24 oktober 2026."></a>Is something not right? Do you see an error, or has a rate changed? Report it via the contact page, and we will look into it.
Free website scan
How do you stand compared to your competitors?
I compare your pages with those of your competitors within your industry: what a customer and an AI assistant get to see about your price and conditions, and what you can improve.
Within two working days, you will know where you stand compared to your competitor. No obligations.
Written by
